September 29, 2026
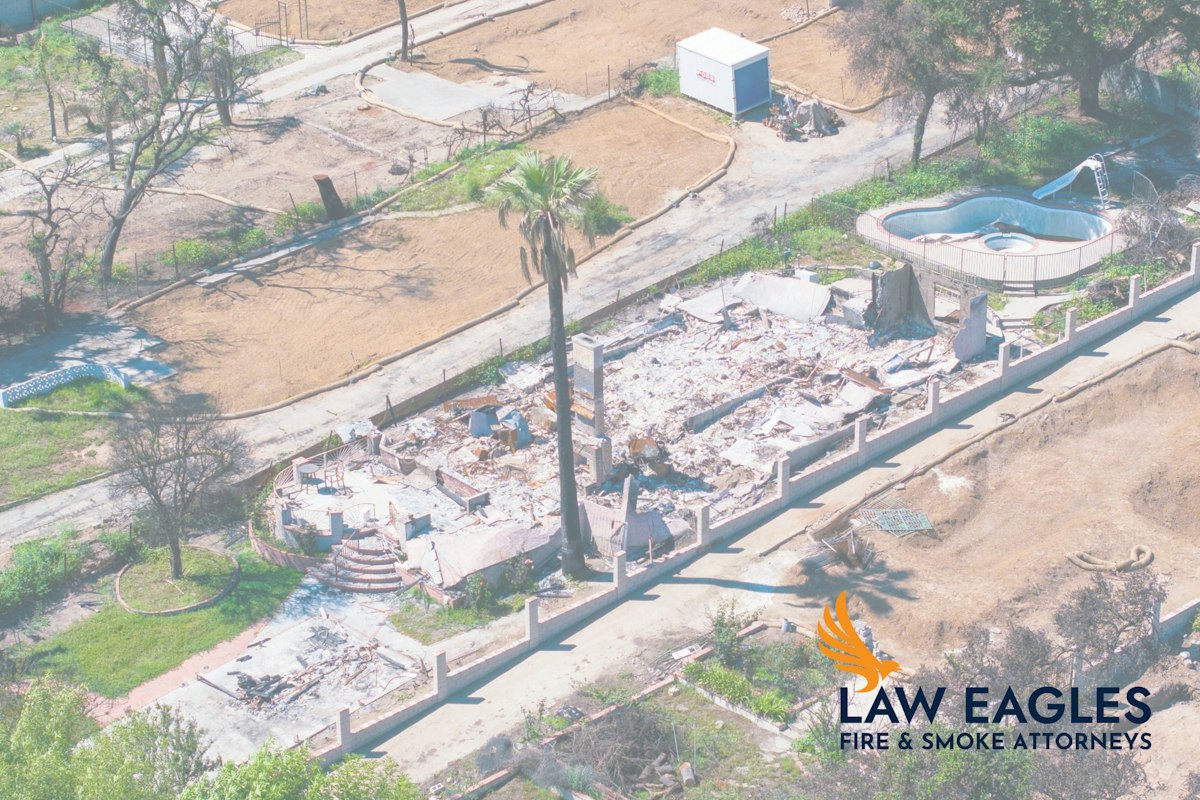
It’s been more than a year and a half since the January 2025 Palisades, Eaton, and Hurst fires tore through Los Angeles. For families whose homes are already rebuilt, that anniversary is a milestone. For thousands of others, it’s a reminder that their claim still isn’t resolved. The insurance fight didn’t end when the fires went out.
Here’s where things actually stand for LA wildfire insurance claims heading into fall 2026, what’s changed since the fires, and what to do if your file is still open.
More Than a Year Later: Where Palisades, Eaton, and Hurst Claims Stand
Of the roughly 40,000 insurance claims filed after the January 2025 fires, a significant share remain unresolved this far out. Rebuild timelines in Los Angeles have been slowed by permitting backlogs, contractor availability, and debris removal schedules. Those factors are largely outside a homeowner’s control, but insurers don’t always account for them when they set expectations around how long benefits should last.
The New Legal Protections That Have Emerged Since January 2025
The scale of insurer mishandling after these fires helped drive real legislative change. AB 1795, the Smoke Damage Recovery Act, was signed on September 15, 2026. It requires insurance companies to pay for smoke damage testing, generally inspect smoke-damaged homes within 30 days, and keep paying Additional Living Expenses until a home is remediated and cleared for occupancy. Those standards didn’t formally exist when the January 2025 fires happened. California Insurance Code § 2060 also gives homeowners displaced by a declared state of emergency at least 24 months of ALE coverage, with up to 12 more months when delays like permitting backlogs and debris removal are outside their control. If your insurer told you your ALE benefits were simply over on a fixed date, that may not be the end of the conversation.
Common Reasons Claims Are Still Open in 2026
A few patterns show up again and again in claims that are still unresolved this far out. Rebuild cost estimates from insurers often haven’t kept pace with actual 2026 Los Angeles construction pricing, leaving a real gap between what’s been offered and what it costs to rebuild. Scope-of-loss disputes are common, especially around smoke and structural issues that weren’t obvious in an initial inspection. ALE payments have been cut off in some cases before a home was anywhere close to livable. And multiple adjuster reassignments have left some homeowners re-explaining their claim from scratch more than once.
If Your Insurer Is Trying to Close Your File Before You’re Made Whole
Insurance companies have an incentive to close old claims, especially as a fire event moves further into the past and gets less public attention. That doesn’t mean your claim is actually finished. If you’re being pushed toward a final settlement that doesn’t reflect your actual rebuild costs, or your insurer is treating an old ALE cutoff date as final despite ongoing delays outside your control, you’re allowed to push back. And you don’t have to do it alone.
Resources Available to LA Fire Survivors Right Now
The California Department of Insurance maintains resources specifically for wildfire survivors, including guidance on the claims process and how to escalate a dispute. The California Wildfire Fund also exists as a backstop resource tied to utility-caused fire liability. These resources are worth knowing about, but they’re not a substitute for having someone advocate specifically for your claim against your specific insurer.
How The Law Eagles Is Still Fighting These Cases
We’ve been representing LA wildfire victims since these fires broke out, through denied claims, underpaid settlements, bad faith disputes, and total loss battles that are still ongoing more than a year and a half later. A claim that’s still open in 2026 isn’t a lost cause. It’s often a claim that hasn’t had the right advocate pushing back yet. We work on contingency: no fee unless we win.
Call (833) 324-5399 or schedule a free consultation if your LA fire claim is still unresolved.
Frequently Asked Questions About LA Wildfire Claims in 2026
Is it too late to file an LA wildfire insurance claim?
Probably not, but the clock is running. For losses tied to a declared state of emergency, California gives you 24 months from the date of loss to file a lawsuit against your insurance company under Insurance Code § 2071. For the Palisades and Eaton fires, that date is January 7, 2027. The clock can pause while your insurance company is still handling your claim, so the deadline isn’t automatic, but don’t count on it. Our guide to California fire insurance claim deadlines explains how it works. Talk to an attorney about your specific timeline before assuming you have more time.
What if my insurer already closed my file?
A closed file isn’t necessarily final, especially if you discover additional damage, your rebuild costs exceed what was paid, or you believe your claim was underpaid. An attorney can review whether you have grounds to reopen or dispute the resolution.
Can I reopen a settled claim if I discover more damage?
It depends on the terms of your settlement and policy, but discovering damage that wasn’t part of the original scope of loss, particularly hidden smoke or structural damage, is a common reason claims get revisited.
Where can LA fire survivors get help right now?
The California Department of Insurance offers wildfire-specific consumer resources, and the California Wildfire Fund provides a backstop tied to utility liability. For help with your specific insurance claim, an attorney experienced in California fire claims can advocate directly on your behalf.